PSX gains 663 points as central bank increases policy rate
Updated 4 hours ago
Governor says economic outlook has changed significantly amid rising global commodity prices, geopolitical uncertainty
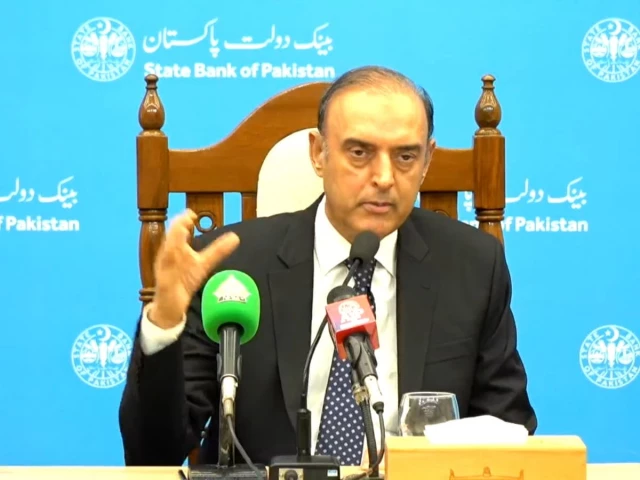
The State Bank of Pakistan (SBP) raised its key policy rate by 50 basis points to 12% on Monday, marking its first increase since April amid rising energy costs linked to the US-Iran war.
"The Monetary Policy Committee (MPC) decided to increase the policy rate by 50 bps to 12 per cent in its meeting today, with the majority decision of nine out of ten members, with effect from October 27, 2026," the central bank said in a statement.
The MPC said the intensifying conflict in the Middle East and diminishing prospects of a near-term resolution were keeping global energy prices persistently high.
"While the impact of this global shock on the domestic economy has remained contained so far amidst proactive monetary policy adjustment and continued fiscal discipline, geopolitical developments have worsened the inflation outlook as compared to the earlier assessment," it added.
The central bank said its outlook for the external account and economic growth remained broadly unchanged, although risks to both had increased.
Against this backdrop, the MPC said the rate increase was necessary to anchor inflation expectations, limit the secondary effects of the ongoing supply shock and bring inflation within its target range of 5% to 7%.
"This will help preserve macroeconomic stability, which is necessary for sustainable economic growth," it said.
The Monetary Policy Committee (MPC) decided to increase the policy rate by 50 bps to 12 percent in its meeting today, with the majority decision of nine out of ten members, with effect from October 27, 2026.
— SBP (@StateBank_Pak) October 26, 2026
For details: https://t.co/9AzpnhseRS pic.twitter.com/FsR8gt2WMX
Addressing a press conference following the MPC meeting, SBP Governor Jameel Ahmad said crude oil prices hovering around $100 per barrel had increased pressure on domestic prices.
He said nine of the MPC's 10 members voted in favour of increasing the policy rate, reflecting growing concerns over inflation and external economic risks.
The governor said the economic outlook had changed significantly since the previous monetary policy meeting, with rising global commodity prices and geopolitical developments adding to uncertainty.
Ahmad said earlier assessments during July and August had suggested that inflation would remain around 7% towards the end of the year, adding that recent developments had altered that outlook, and bringing inflation down to the previously anticipated level was now expected to take longer.
He said core inflation had shown improvement, but warned that higher energy prices could generate secondary inflationary effects in the coming months.
The governor noted that global oil and commodity price increases were affecting domestic inflation and putting additional pressure on Pakistan's external account.
Ahmad said rising global commodity and oil prices were expected to affect the country's current account deficit projections, saying despite these pressures, the central bank expected the current account deficit to remain between 0% and 1% of gross domestic product (GDP).
He said workers' remittances were expected to improve, supported by measures aimed at encouraging overseas Pakistanis to send money through formal banking channels.
According to the governor, Pakistan received $10.9 billion in remittances during the first quarter of the current financial year.
He said full-year remittances were now expected to reach between $44 billion and $45 billion.
Ahmad also referred to a remittance reward scheme, saying the initiative was expected to support inflows in the coming months.
The governor said Pakistan's export performance had shown signs of improvement, although growth remained below expectations, adding that projected exports of between $32.5 billion and $33 billion during the current financial year.
However, he warned that the country was facing considerable pressure on imports due to rising international commodity and energy prices.
Ahmad said the import bill was expected to reach approximately $71 billion during the financial year, saying that the higher import costs could complicate efforts to manage the external balance, despite anticipated improvements in remittances and exports.
Last month, the MPC kept the policy rate unchanged at 11.5%, in line with market expectations. The decision was the third consecutive hold after the 100-basis-point increase in April, the first hike in nearly three years. The July meeting had also left the rate at 11.5%, citing an improved macroeconomic outlook tempered by risks from renewed conflict in the Middle East.
In July, the MPC decided to maintain the policy rate at 11.5%, citing an improved macroeconomic outlook tempered by elevated risks from the renewed conflict in the Middle East. The committee assessed that earlier de-escalation had lowered global oil prices and eased supply-chain pressures, contributing to some improvement in recent indicators.
The MPC noted that proactive policy management and fiscal consolidation had helped absorb the ongoing supply shock and preserve stability. It reiterated its commitment to bringing inflation into the 5-7% medium-term target range and said the current stance remains appropriate.
The MPC in June kept the policy rate unchanged at 11.5%, in a cautious approach amid mixed signals on inflation and external risks.
Market experts had shown divided opinions ahead of the announcement. According to a poll by Topline Securities, 49% of respondents anticipated no change, while another 49% expected a hike, with 34% forecasting a 50bps increase and 15% a 100bps rise. Only 2% predicted a cut of up to 50bps.
In March, amid the outbreak of the United States-Israeli war against Iran and heightened regional geopolitical tensions, the MPC decided to maintain the policy rate unchanged at 10.5%.
The stance reflected caution over potential imported inflation pressures from surging global energy prices, triggered by the US-Iran tensions that drove Brent crude up sharply to around $108 per barrel. The cautious pause in March was seen as support for ongoing macroeconomic stability efforts, building on prior rate reductions (including the 50 bps cut to 10.5% in December 2025), while allowing time to monitor energy price dynamics, domestic inflation trends, and external account resilience.
Later, in a move that defied market expectations, the MPC announced a sharp 100 basis point increase in the policy rate in April, raising it to 11.5%. The SBP’s move signalled a decisive pivot, prioritising inflation anchoring over near-term growth support, even as the economy posted a 3.89% GDP expansion in Q2 and a $1.07 billion current account surplus in March.
This material may not be published, broadcast, rewritten, redistributed or derived from. Unless otherwise stated, all content is copyrighted © 2026 The Express Tribune.
COMMENTS
Comments are moderated and generally will be posted if they are on-topic and not abusive.
For more information, please see our Comments FAQ