Closing gateway to Central Asia
Updated 34 minutes ago
Stop trying to change how households save; start offering them same assets through regulated products
Pakistan's national savings were 14.1% of GDP in FY2026, according to the Economic Survey. Bangladesh is close to 29% and India close to 30%. The comparison is made every year, and it usually ends with the view that the Pakistani household has to be taught to save.
I have never agreed with that view. A household that has money left over at the end of the month keeps some of it as cash at home and puts the rest into dollars, gold, a plot or, in the village, a buffalo. Younger people have started buying crypto. Millions belong to a committee, where 10 people put in a fixed amount every month and one of them takes the pot.
This is saving, even though very little of it ends up as a bank deposit, a National Savings certificate or a mutual fund unit. The State Bank's 2021 survey found 55% of respondents saving at home and 37% in committees. Cash in circulation was Rs9.1 trillion last year. The Competition Commission estimates that Pakistan consumes 60 to 90 tonnes of gold a year, with more than 90% of the trade outside formal channels. Savings held this way cannot be lent to a small business or used to fund a mortgage, and that is the real cost to the economy.
Customer's lens
To understand why people save like this, look at it through the customer's lens. Take a saver who had $1,000 in September 2021. If she converted it into rupees and kept the cash at home, as most savers do, she had about Rs168,000. At about Rs278 to the dollar, that cash is worth roughly $600 today. A bank savings account would have paid her profit over those years, but more than half of our savers do not use one.
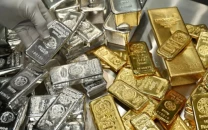
Had she simply held the dollars, she would still have $1,000, less American inflation. Had she bought gold, she would have about $2,200, because gold has gone from around $1,750 an ounce to around $3,865, even after falling by more than a quarter from its peak in January. Bitcoin, bought at about $47,260, would have given her roughly $1,360 at the recent price of about $64,500. A month ago, the same holding was worth over $1,700, which tells you how much risk she would have carried.
Property and livestock cannot be added to this comparison, because Pakistan has no national index based on actual transactions that would tell us what $1,000 put into a plot or into cattle in 2021 is worth now. These are among the assets people trust most, and we have the least data on them.
Inflation was 9.6% in October, after two months in double digits. A household that kept rupees in a trunk through the last five years knows what that means without being told. It moved into gold and dollars because they protected its money, and on these numbers it was right to do so. So I would stop asking people to change how they save, and start offering them the same assets through regulated products.
What formalisation looks like
The committee is the obvious place to begin. A bank or a fintech can run it digitally, with contributions deducted from a wallet or an account and every member able to see who has paid, who has missed and who has drawn. A member who completes a committee has built a payment record, and that record should count towards her credit score.
Gold should not require several hundred thousand rupees for a biscuit. A customer should be able to buy Rs500 or Rs1,000 worth through her wallet, with the gold held by an independent custodian, insured and audited, and with the price at which she can sell shown on her screen.
People will hold dollars whether we approve or not. A regulated digital foreign currency savings product, within the State Bank's rules, is a better outcome than notes bought in the informal market and kept in a locker. On crypto, Chainalysis ranked Pakistan third in the world for adoption in 2025, and the country now has a virtual assets regulator. What matters from here is whether that activity moves from offshore exchanges to licensed local platforms.
Property works the same way. Very few people can buy a Rs30 million apartment, but a great many could put Rs10,000 into a regulated real estate structure. Livestock can be handled similarly, with tagged and insured animals kept on professionally run farms and investors sharing in the return.
Eventually all of this should sit in one place on the phone. A customer with Rs5,000 could put Rs1,000 each into a savings account, gold, dollars, property and one other regulated investment, with every provider licensed and every holding saleable when she needs the money.
A caution, before anyone sells this to millions
I would add a caution from experience. When a payment fails, the customer is annoyed, but when a savings product fails, a family loses its wealth. Custody, audit and the separation of customer assets have to be in place before anyone sells these products to millions. They also fall under the State Bank, the SECP and the virtual assets regulator at the same time, and unless one of them takes ownership, nobody will build them.
We have spent decades trying to get Pakistanis to save in the products the financial system prefers. They have shown us clearly enough what they prefer. If we formalise those choices, their savings will be counted, protected and available for lending. The technology is already here. What is needed is the will.
The writer is chairman of the Pakistan Fintech Network
This material may not be published, broadcast, rewritten, redistributed or derived from. Unless otherwise stated, all content is copyrighted © 2026 The Express Tribune.

COMMENTS
Comments are moderated and generally will be posted if they are on-topic and not abusive.
For more information, please see our Comments FAQ