Building modern financial infrastructure for gold
Updated 1 hour ago
Digitising safe-haven asset can expand financial inclusion
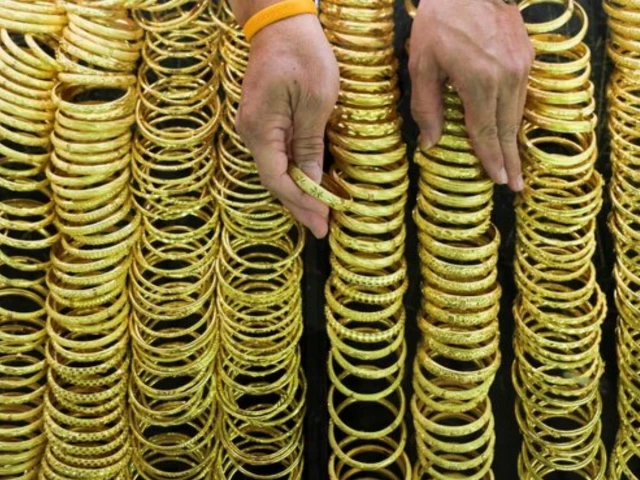
Pakistan has always understood gold. Families buy it for weddings, preserve it for emergencies and pass it from one generation to the next. For many households, it performs functions that the formal financial system has failed to provide adequately: savings, protection against currency depreciation and access to money when circumstances change. The opportunity is to build modern financial infrastructure around a familiar asset and make it accessible to people who cannot afford conventional quantities.
The Competition Commission of Pakistan estimates annual gold consumption at 60 to 90 tonnes, with more than 90% of trading outside formal channels. That tells us something important. We do not have to create demand. Demand already exists. What is missing is a convenient, transparent way for ordinary Pakistanis to acquire small amounts, hold them safely and sell them when needed. Digitisation can address each of these requirements, provided the underlying structure is sound.
My experience in financial inclusion has taught me that a product will achieve scale only when it fits the customer's circumstances. For lower-income households, four requirements matter: security, transparency, liquidity and trust. Alongside these, the entry amount must be affordable. Someone who can spare Rs500 should not have to wait until they can purchase a coin or a bar. Equally, someone putting aside money today must know that it can be accessed tomorrow if a household need arises.
Consider how a digital gold savings account could work. A customer buys Rs1,000 of gold through a mobile wallet. The money purchases a fractional holding in physical gold maintained with an independent custodian. The next day, the customer adds Rs500, then another Rs2,000 the following week. Each purchase adds a clearly recorded weight to the account. The customer is accumulating gold according to available cash rather than having to organise cash around the size of a gold product.
The customer then has a choice. Someone saving for a daughter's wedding can continue buying until the balance reaches the quantity required for physical delivery. Someone facing a medical bill can sell part of the holding and retain the rest. Another customer may sell the entire balance. The ability to sell anytime should be central to the proposition, with clear arrangements for execution and settlement. Physical delivery is an option for the saver, rather than a condition for accessing value.
This is where liquidity becomes critical. A low-income customer cannot necessarily predict when money will be needed. School fees, medical expenses and interruptions in earnings do not follow an investment calendar. If buying takes seconds but selling involves unexplained delays, the product has failed an essential test. Customers should see the available sale price, know when proceeds will reach their account and receive them reliably. Providers must arrange the liquidity required to honour this commitment as their customer base grows.
Security begins with the underlying asset. Every gram credited to customers must be supported by an equivalent quantity of physical gold. That gold should be independently held, insured and audited, with customer ownership legally protected and separated from the platform's own assets. Otherwise, we risk creating a digital balance that looks reassuring while leaving the saver exposed to the operating company's financial problems. Technology can record ownership, but it cannot substitute for reserves, custody and enforceable rights.
Transparency requires more than displaying a daily gold rate. The customer should see the weight owned, its rupee value, the purchase price, the sale price and every applicable charge. The difference between buying and selling prices must be visible before a transaction. Physical delivery costs and minimum delivery quantities should also be clear. Gold prices can fall; a secure holding does not guarantee a profit. Customers must understand both the market risk they accept and the service for which they pay.
Trust develops when these arrangements work consistently. An audit helps, but so does a successful sale, a timely payment and a complaint resolved without difficulty. Women deserve particular attention because household ownership does not always mean individual control. An account should establish whose gold it is, who can sell it and where the proceeds go. The convenience of digital access should strengthen the owner's control. It should not introduce another intermediary between a woman and an asset that belongs to her.
There are different ways to build this infrastructure. One model uses certificates recording fractional ownership of vaulted gold. Another represents that ownership through digital tokens. Both require appropriate regulatory approval, clear custody arrangements and protection for customers. Blockchain may support record keeping, but the customer should not need to understand it to save. The practical questions remain straightforward: does my gold exist, what does it cost, can I take delivery, and can I sell it when I need the money?
Distribution should use the accounts and applications people already have. Banks, wallets and fintechs could allow customers to purchase small quantities manually or through regular savings instructions. Gold-backed lending can subsequently provide another option for customers who prefer to borrow against their holdings. However, savings must first work independently: easy purchases, protected ownership and dependable sales. A limited pilot should test these functions, including withdrawals during busy periods, before providers expand to millions of customers across the country.
For providers, the commercial test is equally important. Small balances require low costs, efficient custody and sufficient transaction volumes. An expensive product will exclude precisely the customers it is intended to serve. Scale must improve affordability while preserving these safeguards.
Pakistan's gold opportunity therefore extends beyond lending against jewellery already sitting in a household cupboard. It includes helping people build an asset gradually, in amounts they can afford, while retaining the freedom to change their minds or meet an emergency. Security, transparency, liquidity and trust are the foundations. Small quantities make participation possible. Reliable selling makes participation practical. We have already seen how digital distribution can widen financial access. The next step is to apply that capability to an asset Pakistanis understand and give the customer control over buying, holding, taking delivery or selling.
The writer is the chairman of the Pakistan Fintech Network

This material may not be published, broadcast, rewritten, redistributed or derived from. Unless otherwise stated, all content is copyrighted © 2026 The Express Tribune.

COMMENTS
Comments are moderated and generally will be posted if they are on-topic and not abusive.
For more information, please see our Comments FAQ